


Markets were mixed last week, though persistent pressure on technology stocks made the week feel more challenging for some investors.
The Standard & Poor’s 500 Index lost 0.47 percent, while the Nasdaq Composite Index declined 0.71 percent. The Dow Jones Industrial Average gained 0.41 percent. The MSCI EAFE Index, which tracks developed overseas stock markets, fell 1.58 percent.1,2
Tech Leads Both Ways
The week began with an AI-led rebound as investors looked ahead to a heavy slate of corporate earnings reports. On Tuesday, investors cheered the first wave of corporate results and falling oil prices, which helped boost investor sentiment.
Tech swung back into favor midweek as investors applauded reports that two of the largest megacap tech firms formed a committee to evaluate a potential merger, lifting all three averages. The Nasdaq gained more than 1 percent, while the S&P posted its third straight winning close.3,4
Boomerang Effect
But the boomerang started to come back on Thursday as AI debt worries returned while oil prices rose again amid fresh geopolitical concerns. The Nasdaq slid more than 2½ percent over the session, while the S&P fell more than 1 percent, posting their steepest daily declines since June and July, respectively.5
The week wrapped up with technology stocks again in the spotlight due to persistent AI-related worries. The Dow closed Friday down more than 1 percent, while the S&P 500 and Nasdaq were under pressure into the close.6
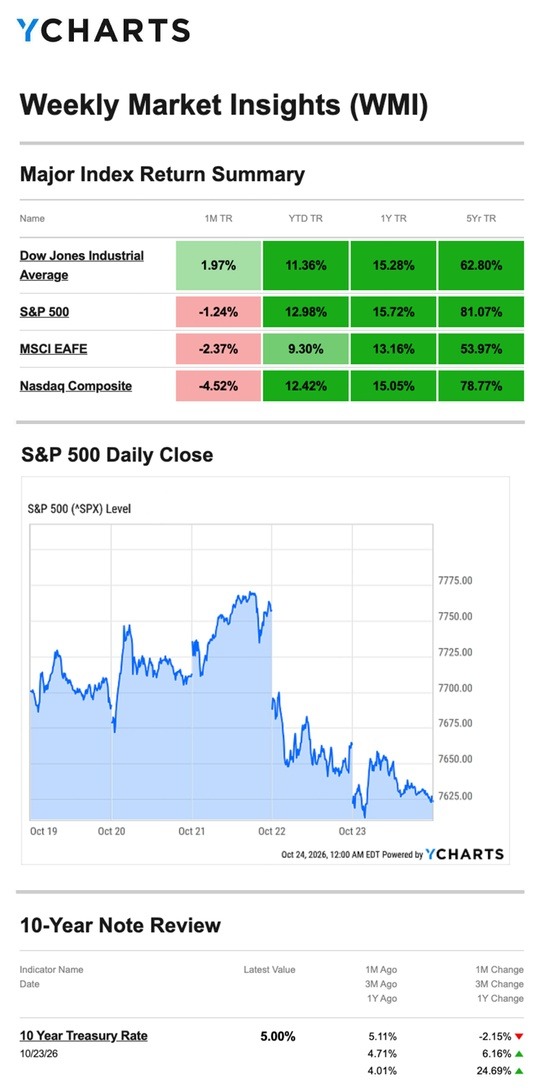
Source: YCharts.com, October 24, 2026. Weekly performance is measured from Monday, October 19 to Friday, October 23. TR = total return for the index, which includes any dividends as well as any other cash distributions during the period. Treasury note yield is expressed in basis points.
Housing Watch
With everything going on last week, the housing market didn’t get much coverage. But there were some important housing developments.
First, housing starts fell 5.2 percent in September over the prior month, below expectations for a 2 percent rise. It was the second straight month when economists expected starts to rise, and instead they fell, and the third consecutive month of declines.7
Meanwhile, pending home sales fell to their lowest level on record in September in part due to an increase in mortgage rates.8
Week Ahead
The week ahead brings a busy schedule of economic reports that will help provide a clearer picture of how the economy is performing as we head into the final months of the year. Recent reports suggest the economy remains relatively strong, but inflation continues to be a concern, leaving questions about the Federal Reserve’s next steps.
Tuesday’s reports on durable goods orders, consumer confidence, and new home sales will offer a look at business spending, how consumers are feeling about the economy, and the housing market. Higher borrowing costs and affordability challenges continue to make buying a home difficult for many Americans.
Wednesday’s Federal Reserve meeting will be a major focus for investors. Along with its interest rate decision, the Fed’s comments will be closely watched for clues about how it plans to balance inflation concerns with economic growth and employment.
Thursday brings several key reports, including the advanced estimate of third-quarter Gross Domestic Product (GDP), which measures overall economic growth, and the September Personal Consumption Expenditures (PCE) inflation report, the Fed’s preferred measure of inflation. Updates on consumer spending and unemployment claims will also help show how households and the job market are holding up.
The week wraps up on Friday with the Chicago PMI, which will provide an update on regional manufacturing activity and whether recent improvements are continuing. The third-quarter Employment Cost Index will also offer insight into changes in wages and how they may affect inflation. Together, these reports should offer a better understanding of where the economy is headed and monetary policy outlook through the end of the year.
This Week: Key Economic Data
Tuesday: Durable Goods. S&P Cotality Case-Shiller Home Price Index. New Home Sales. Consumer Confidence (Conference Board). Federal Open Market Committee (FOMC) Meeting, Day 1.
Wednesday: Trade Balance in Goods. Wholesale Inventories. Retail Inventories. FOMC Meeting, Day 2 / Fed Interest Rate Decision.
Thursday: Gross Domestic Product (GDP). Weekly Jobless Claims. Personal Consumption Expenditures (PCE) Index.
Friday: Employment Cost Index.
Source: Investor’s Business Daily - Econoday economic calendar: October 23, 2026.
The Econoday economic calendar lists upcoming U.S. economic data releases (including key economic indicators), Federal Reserve policy meetings, and speaking engagements of Federal Reserve officials. The content is developed from sources believed to provide accurate information. The forecasts or forward-looking statements are based on assumptions and may not materialize. The forecasts are also subject to revision.
This Week: Companies Reporting Earnings
Monday: Verizon Communications Inc. (VZ), Welltower Inc. (WELL), Cadence Design Systems, Inc. (CDNS)
Tuesday: Visa Inc. (V), The Coca-Cola Company (KO), The Boeing Company (BA), S&P Global Inc. (SPGI), Corning Inc. (GLW), HCA Healthcare, Inc. (HCA)
Wednesday: Alphabet Inc. (GOOG / GOOGL), Microsoft Corporation (MSFT), GE Vernova Inc. (GEV), KLA Corporation (KLAC), Amphenol Corporation (APH), T-Mobile US, Inc. (TMUS), ServiceNow, Inc. (NOW), Fortinet, Inc. (FTNT), Automatic Data Processing, Inc. (ADP), Phillips 66 (PSX), Equinix, Inc. (EQIX)
Thursday: Amazon.com, Inc. (AMZN), Eli Lilly and Company (LLY), Mastercard Incorporated (MA), Intel Corporation (INTC), Merck & Co., Inc. (MRK), Caterpillar Inc. (CAT), Sandisk Corporation (SNDK), Gilead Sciences, Inc. (GILD), Bristol Myers Squibb Company (BMY), Altria Group, Inc. (MO), Stryker Corporation (SYK), Starbucks Corporation (SBUX)
Friday: ExxonMobil Holdings Corporation (XOM), AbbVie Inc. (ABBV), Chevron Corporation (CVX), General Dynamics Corporation (GD)
Source: Zacks, October 23, 2026. Companies mentioned are for informational purposes only. It should not be considered a solicitation for the purchase or sale of the securities. Investing involves risks, and investment decisions should be based on your goals, time horizon, and risk tolerance. The return and principal value of investments will fluctuate as market conditions change. When sold, investments may be worth more or less than their original cost. Companies may reschedule their earnings reports without notice.
Footnotes and Sources
1. WSJ.com, October 23, 2026
2. Investing.com, October 23, 2026
3. CNBC.com, October 20, 2026
4. CNBC.com, October 21, 2026
5. CNBC.com, October 22, 2026
6. WSJ.com, October 23, 2026
7. WSJ.com, October 20, 2026
8. WSJ.com, October 20, 2026
This content was developed by FMG Suite and Cambridge Investment Research, Inc. from sources believed to be reliable. This content is provided for informational purposes only and should not be construed or acted upon as individualized investment advice. It should not be considered a recommendation or solicitation. Information is subject to change. Any forward-looking statements are based on assumptions, may not materialize, and are subject to revision without notice. The information in this material is not intended as tax or legal advice.